UK SMEs with overseas customers, suppliers, contractors, or non-resident directors often need account, card, and payment services that work across jurisdictions. Yet high-street banks and conventional business-account providers can be less suited to companies with complex ownership structures, multi-currency requirements, or frequent smaller-value international transfers.
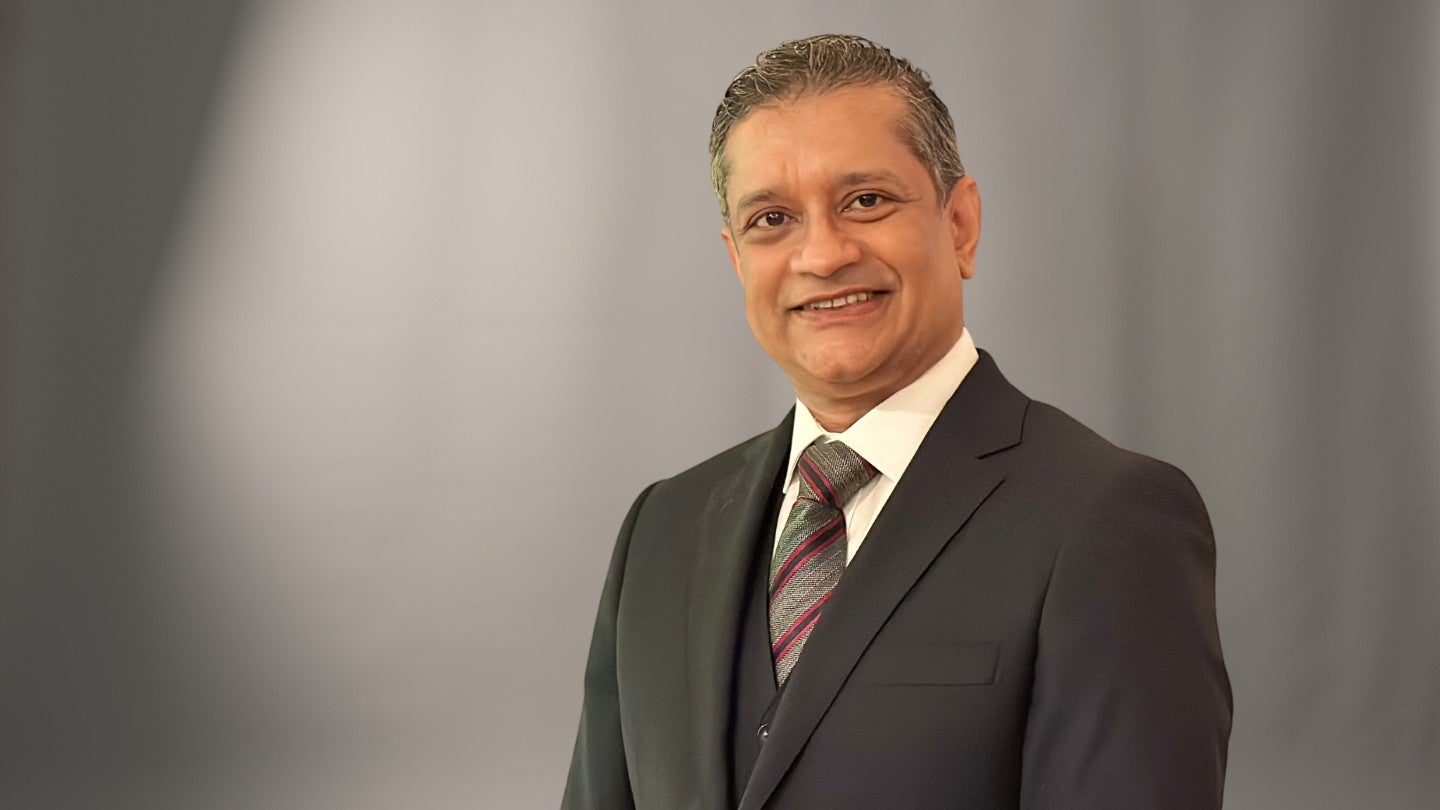
In this interview, Amaiz CEO Steve Taklalsingh outlines the company’s target for 20% growth in business-account applications, its focus on local payment routes alongside SWIFT, and how virtual-card issuing and APIs are being used to automate payment operations.
Go deeper with GlobalData
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
EPI: Could you outline your core offerings, and share your current active user counts and annual transaction volumes?
Steve Taklalsingh: Amaiz provides multi-currency UK business accounts, payment cards and international payments, primarily for UK SMEs operating domestically and across borders. We also support eligible businesses from the EEA, Switzerland and other international markets that approach us directly, as well as sole traders and individuals. Our portfolio currently includes around 3,000 accounts, with approximately 85% active.
Amaiz customers can hold accounts in GBP, EUR, USD, CHF, AED and HKD. Payments are supported through UK Faster Payments, SEPA and SEPA Instant, SWIFT and local payment methods, with mass-payment capabilities for businesses paying multiple suppliers, contractors and other recipients.
As a Mastercard principal member, Amaiz provides physical and virtual cards, dedicated BINs, merchant acquiring and payouts to Visa and Mastercard cards.
For a UK business with overseas customers, suppliers or contractors, that integration can simplify payment operations, improve transparency over spending and reduce manual reconciliation.
EPI: Entering your eighth year in the market, what specific account growth target have you set for this financial year?
Steve Taklalsingh: Amaiz is targeting around 20% growth in business account applications this year. In the UK, that means competing for businesses that have a clear reason to change or add an additional payments provider, not simply relying on the formation of new companies.
The British Business Bank’s Small Business Finance Markets Report 2026 shows new business formation grew by just 1% in 2025, so the pool of new companies looking for their first account is barely growing.
Much of our growth has to come from businesses actively looking for a better fit than their current provider.
Our objective is quality of growth as well as volume. We are prioritising internationally active businesses, digital advertising agencies with significant card or campaign spend, technology companies paying overseas contractors, and UK companies with non-resident directors that often struggle to open accounts with high-street banks.
We want customers who use Amaiz for account services, international payments and cards working together. That’s where we add the most value.
EPI: With payment rails already spanning 96 countries, which new geographic corridors are prioritising your expansion plans?
Steve Taklalsingh: SWIFT already gives our customers broad global reach. Amaiz’s local payment methods, which route a transfer through the recipient country’s domestic payment system rather than the SWIFT network, provide an additional, faster and lower-cost option, now available in 96 countries.
Key local corridors include bank account payouts to India, Pakistan, Bangladesh, the Philippines, Vietnam, Thailand, Nigeria, Turkey and China, as well as mobile wallet payouts in markets such as Pakistan, Bangladesh, the Philippines, Vietnam, Kenya and The Gambia.
SWIFT remains the right route for larger transfers, but intermediary fees weigh most heavily on smaller payments. Through Amaiz’s local routes, a €1,000 transfer can cost €8.99 and typically arrives within 24 hours.
Where we expand next will be driven by where our customers are already sending payments.
EPI: To help us gauge your enterprise volume, how many corporate Mastercards are currently active through your API?
Steve Taklalsingh: Amaiz issued about 70,000 cards over the past year, the majority of them virtual. Our infrastructure supports programmes issuing up to 10,000 cards per month.
As a Mastercard principal member, we also offer dedicated BINs and card issuing as a service for companies launching their own programmes.
Digital advertising is our clearest use case. Agencies may need to separate spend across multiple platforms, campaigns and clients. Put all of that on one company card and reconciliation becomes a monthly problem. Virtual cards let them allocate spend by campaign or client, and our API connects issuing directly to their existing systems.
The number of cards isn’t the point. Control is.
EPI: Innovation moves quickly in fintech; what new products or features are currently in your development pipeline?
Steve Taklalsingh: Our priority is to make businesses work more seamlessly. The biggest gains come from connecting what businesses already use, including accounts, transfers, cards and financial data, so finance teams stop stitching systems together manually.
APIs are what make that possible. Through Amaiz’s APIs, companies can manage wallets, initiate transfers, and issue and control cards, with webhooks providing automated updates on every financial event. That’s where business banking is heading: less a destination, more infrastructure that works in the background.
Amaiz is also exploring partnerships with appropriately regulated providers that could help businesses receiving digital-asset payments settle costs in traditional currencies.
EPI: While public markets aren’t on your immediate horizon, what milestones will signal your next private funding round?
Steve Taklalsingh: We are not raising external investment, and it is not part of our plans. Our focus is on building the business on a commercially sustainable basis.
Rather than funding milestones, we measure progress by the strength of the business itself: more customers using more than one of our services, adoption of international and local payment routes, growth in API and card-issuing programmes, and onboarding and compliance operations that scale without a proportional rise in cost.
Growth should come from the business, not from a funding round.
EPI: What percentage of your client base is comprised of international founders?
Steve Taklalsingh: International founders running UK companies are one of Amaiz’s core customer segments. A UK company today might have a director in Dubai, customers in Germany and suppliers in Vietnam. Yet many providers still design onboarding around UK-resident directors.
Eligible UK companies with non-resident founders or directors can apply to Amaiz remotely, subject to identity verification, beneficial ownership checks and our compliance requirements. Remote onboarding does not mean reduced scrutiny. It means a process designed for how international businesses actually operate.
EPI: Given your safeguarding framework, how do you address client queries regarding the lack of FSCS deposit insurance?
Steve Taklalsingh: We address it directly and explain the distinction clearly. Amaiz is an FCA-authorised electronic money institution, not a bank, so e-money held with us is not covered by the FSCS in the same way as eligible bank deposits. Customer funds are protected through safeguarding arrangements instead.
Safeguarding works differently from deposit insurance, and we make that clear to customers. Unlike a bank, Amaiz cannot lend customer funds or use them to run the business. They are held in designated safeguarding accounts, separate from our own funds, and are reconciled daily. The FSCS compensates eligible depositors up to £120,000 if a traditional bank fails. Under safeguarding regulations, funds are returned to customers through an insolvency process rather than as a compensation payment, so the timing and amount returned depend on that process.
Customers deserve to understand both the protection and its limits.